UK Retail Sector Navigates Financial Tightrope Following Chancellor John Healey’s First Budget

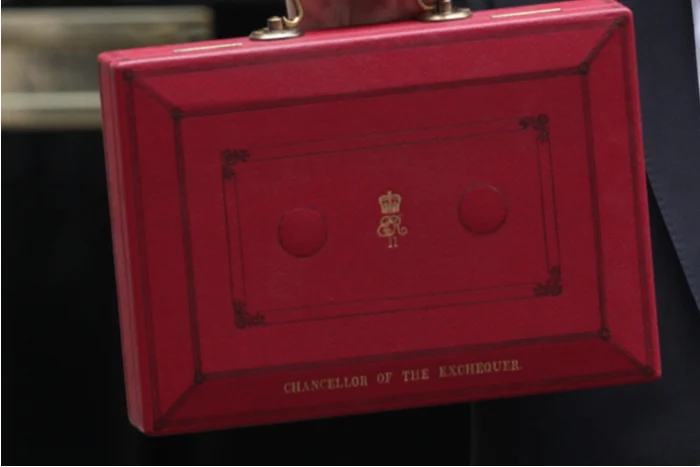
UK retailers are facing a complex economic landscape following Chancellor John Healey’s inaugural Budget, unveiled on Wednesday, 28 October. The fiscal package attempts to balance the urgent need for high-street revitalization with the harsh realities of a rising wage bill and persistent inflationary pressures. While the government has introduced significant relief on property taxes and energy costs, these measures are juxtaposed against mandatory increases in employment expenses, leaving the retail sector to navigate a precarious path toward sustained profitability.
The Budget arrives at a critical juncture for the British economy. Following a period of aggressive interest rate hikes and subdued consumer spending, the retail sector has been lobbying for structural changes to the business rates system—a tax regime often criticized for penalizing physical store operators compared to their online-only counterparts. Healey’s announcement signals a move to rectify these imbalances, though the fiscal burden of these concessions is being partially redistributed across the business community.
A Chronology of the 2027 Fiscal Measures
The government’s strategy is mapped out over the next 18 months, with a phased implementation designed to avoid sudden shocks to operational liquidity.
- October 2027: New compliance regulations take effect, mandating that online marketplaces assume responsibility for the collection of Value Added Tax (VAT) on behalf of third-party UK sellers.
- April 2027: The National Living Wage increases by 3.9% to £13.21 per hour. Simultaneously, the British Industrial Competitiveness Scheme launches, promising up to 25% reductions in electricity costs for over 10,000 industrial and commercial entities.
- July 2027: The government plans to defer the RPI-linked increase in fuel duty, extending the current 5p reduction and ensuring that petrol and diesel prices remain suppressed relative to previous trajectories. Additionally, the temporary VAT cut on electricity is set to expire, marking a potential shift in energy pricing policy.
The Business Rates Overhaul: A Targeted Intervention
At the heart of the retail package is a comprehensive reform of business rates for England’s retail, hospitality, and leisure sectors. The Treasury has confirmed that eligible properties will either see their rates frozen, reduced, or eliminated entirely. This represents a structural shift intended to alleviate the property cost burden that has plagued brick-and-mortar retailers since the 2026 revaluation.
The government estimates that roughly 70,000 additional small businesses will fall beneath the threshold for rates altogether, effectively removing them from the tax base. By the conclusion of this policy rollout, the Treasury anticipates that 50% of all retail, hospitality, and leisure properties will pay zero in business rates.
However, this generosity is not without its cost. To fund the program, the government is introducing a 1p supplement targeted at businesses that benefited from either net reductions or smaller-than-anticipated increases during the last revaluation cycle. This "Robin Hood" style funding mechanism has drawn a mixed response from industry analysts, who suggest it could create friction between different segments of the commercial property market.
Labor Costs and the Wage Pressure Dilemma
While property costs represent a fixed expenditure, labor represents a variable and often the largest operational cost for retailers. The 3.9% increase in the National Living Wage (NLW) to £13.21 per hour and the corresponding rise for 18- to 20-year-olds to £11.27 per hour represent a significant challenge for labor-intensive businesses.
For a full-time employee, this represents an annual gross earnings increase of £910. Across a national retailer with tens of thousands of staff, this shift equates to millions of pounds in additional payroll expenditure. While the 3.9% increase is notably lower than the double-digit percentage hikes seen in previous years, it nonetheless places upward pressure on operating margins at a time when retailers are struggling to pass costs on to inflation-weary consumers.
Retailers have long argued that the cumulative effect of rising payroll taxes, pension contributions, and the NLW increase threatens to stifle job creation. While the government has emphasized that the lower pace of the wage hike is a concession to business viability, the industry maintains that the cumulative burden remains substantial.
Energy and Logistics: The Indirect Cost Relief
Retailers with extensive distribution networks are set to benefit from the extension of the 5p fuel duty cut and the deferral of the RPI-linked fuel duty increase until July 2027. The Treasury claims these moves will result in petrol and diesel prices being 15p per litre cheaper than they would have been under the previous administration’s trajectory.
Beyond fuel, the British Industrial Competitiveness Scheme stands as a major plank in the government’s energy policy. By offering a 25% reduction in electricity bills for over 10,000 eligible businesses, the scheme aims to lower the overheads of large-scale operations. For retailers, this is particularly vital for those operating cold-storage facilities or large-scale warehouse automation systems, where energy consumption is a primary cost driver.
Stimulating the Consumer Engine
The government’s strategy relies heavily on the assumption that if retailers’ costs are lowered and household incomes are supported, consumer confidence will follow. To this end, the Budget introduces a £100 Household Energy Payment for 20 million English households.
The removal of tariffs on over 100 imported goods, including staples such as baked beans and chocolate, is designed to keep grocery inflation in check. By lowering the cost of goods sold (COGS), the government hopes to free up discretionary income for households, theoretically fueling higher transaction volumes during the pivotal Christmas trading period. However, economists warn that if retailers choose to absorb these savings to repair their own margins rather than lowering prices, the stimulative effect on consumer spending may be muted.
Addressing the Digital Playing Field
A significant development in this Budget is the formalization of VAT collection responsibilities for online marketplaces. Starting in October 2027, these platforms will be legally required to collect and remit VAT on behalf of the businesses operating on their sites.
For years, high-street retailers have argued that online competitors were gaining an unfair price advantage by failing to account for VAT, effectively undercutting physical stores that have to account for every penny of their tax obligations. By closing this loophole, the government intends to foster a more equitable competitive environment. While this will increase compliance costs for marketplaces, it is widely viewed as a win for the traditional retail sector, which has been calling for such oversight for over a decade.
Implications and Future Outlook
The broader impact of the Budget is one of measured optimism tempered by fiscal caution. The government has successfully identified the primary levers of retail distress—property costs, energy bills, and competitive imbalances—and has moved to address them.
However, the "verdict" from the retail community is nuanced. The relief provided by business rates is undeniably a lifeline, particularly for smaller independent operators. Yet, the persistent upward pressure on wages ensures that the "cost-of-doing-business" remains high. Analysts suggest that the success of this Budget will be measured by the resilience of consumer spending through the early months of 2028.
If the £100 household energy payments successfully drive footfall into stores, the sector may see a moderate recovery. Conversely, if inflationary pressures remain sticky and wage bills continue to outpace productivity gains, retailers may be forced to look toward further automation or branch closures to maintain profitability.
For the moment, the industry remains in a "wait and see" mode. The structural changes to business rates and marketplace tax compliance are significant, but they represent a transition rather than a transformation. As the 2027 holiday season approaches, the retail sector stands at a crossroads, balancing the relief provided by the Chancellor against the structural headwinds that have defined the post-pandemic economy. Whether these measures provide a genuine catalyst for growth or merely a temporary reprieve will likely be the subject of intense debate in the coming fiscal quarters.