Why solving the fashion industry’s sizing crisis is no longer a technology problem

The fashion industry has spent the better part of the last decade treating the challenge of apparel returns as a technical obstacle, convinced that if the right algorithm or body-scanning tool could be developed, the issue of "fit" would vanish. However, as the retail landscape evolves toward 2027, it has become increasingly clear that the industry’s sizing crisis has transcended its technical roots. While digital tools have advanced significantly, the core friction lies in a disconnect between rigid manufacturing standards, rapidly shifting consumer body types, and the deeply subjective nature of personal preference.
The Financial Scale of the Sizing Crisis
The economic implications of this mismatch are staggering. According to recent data from the National Retail Federation and Statista, returns cost the United States retail sector alone an estimated $890 billion in 2024. Apparel remains the primary driver of these losses, with eCommerce return rates hovering between 10% and 50% depending on the specific market segment and geography.
This "return-first" business model, often fueled by policies offering free shipping and free returns, has birthed the phenomenon of "wardrobing." Consumers, lacking confidence in a brand’s sizing accuracy, frequently purchase multiple sizes of the same garment with the explicit intention of returning those that do not fit. With Adobe’s 2025 holiday statistics confirming that mobile commerce now accounts for more than half of all online retail, the pressure on brands to bridge the gap between a digital image and a physical reality has never been higher.
A Chronology of Failed Tech Solutions
For years, the industry’s approach to this problem has followed a predictable, if largely ineffective, timeline:
- 2015–2018 (The Era of Vanity Metrics): Brands relied on basic size charts and static measurement tables. These were often based on archaic demographic data that failed to account for modern shifts in population health and body composition.
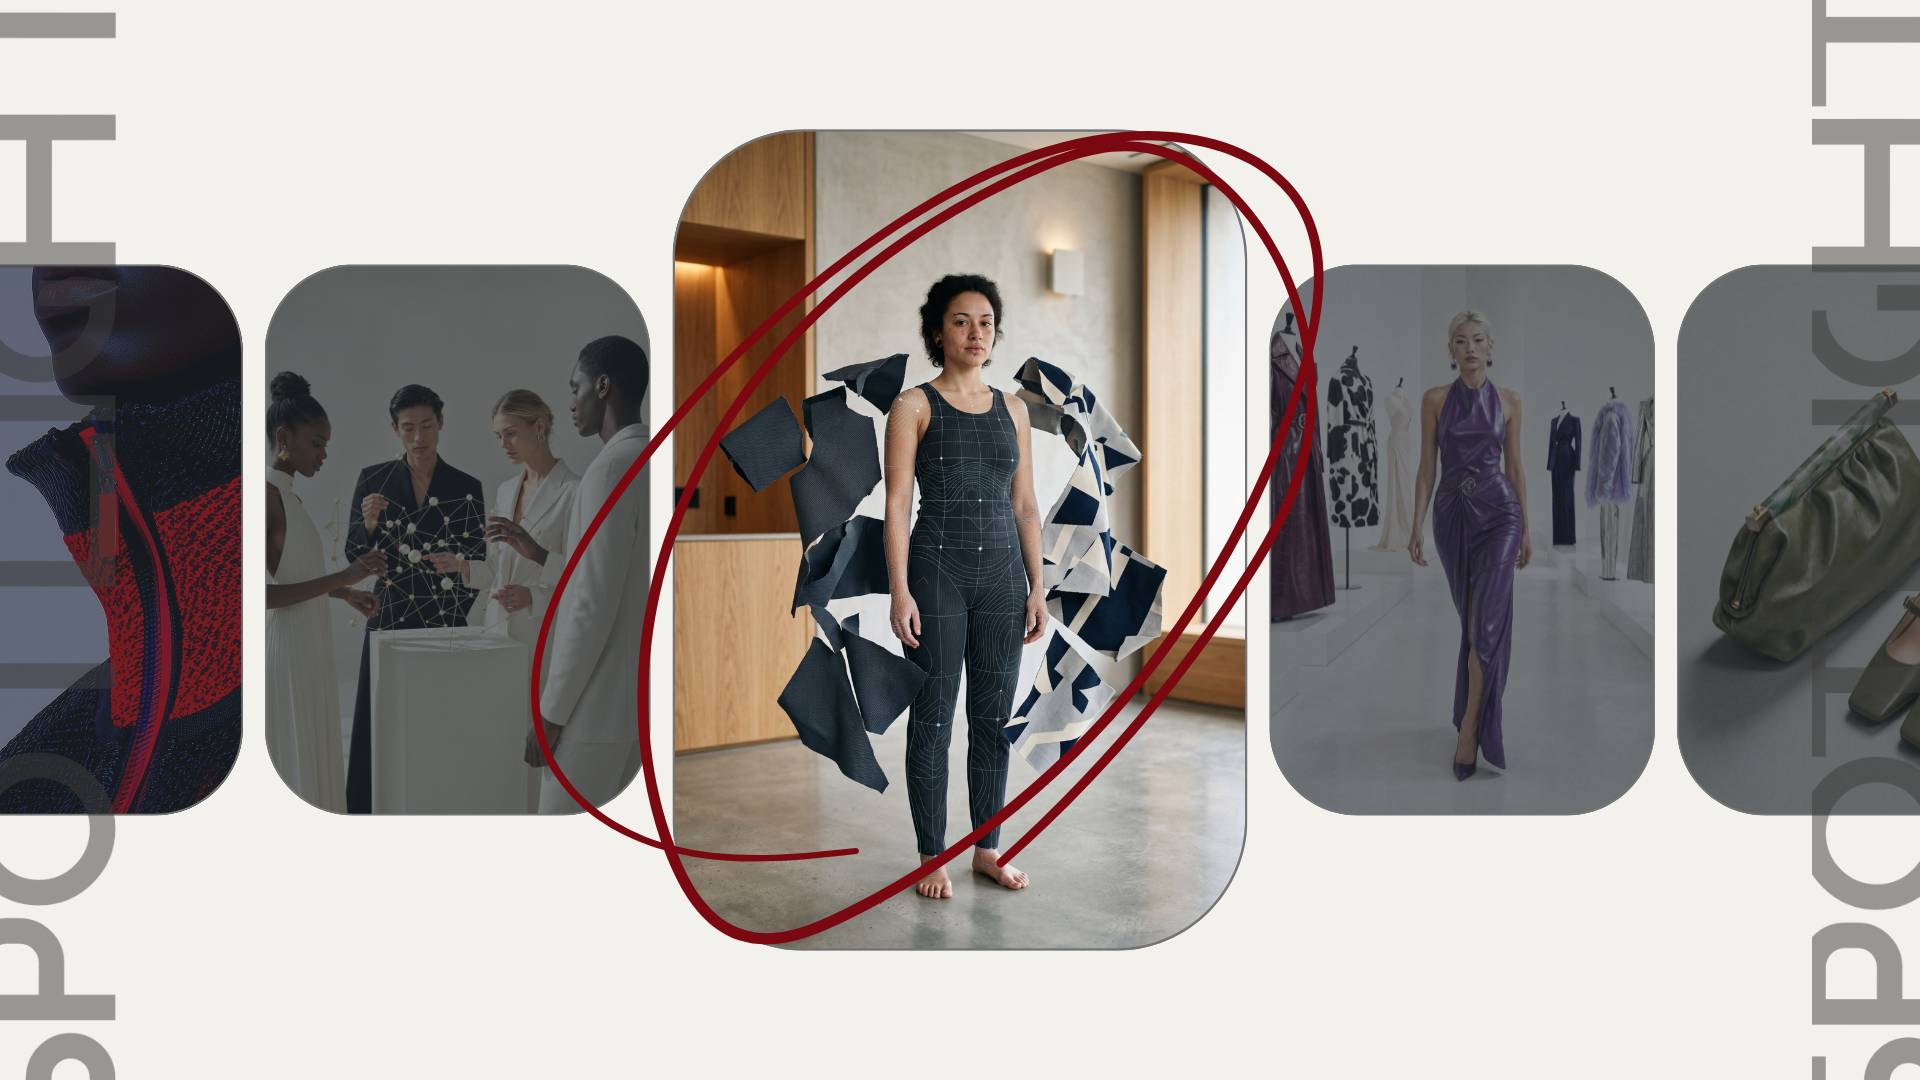
- 2019–2022 (The Push for Biometrics): The industry pivoted toward body scanning, both through specialized kiosks and smartphone-based photographic measurement. The assumption was that capturing a 1:1, millimeter-accurate digital twin of the consumer would solve the mapping problem.
- 2023–2025 (The Rise of 3D Simulation): Focus shifted to virtual try-ons and soft-body avatars. While visually impressive, these tools often ignored the fact that a user’s perception of "good fit" is rarely synonymous with "correct measurement."
- 2026–2027 (The Intelligence Pivot): The current consensus has shifted toward "Fit Intelligence"—platforms that treat body data as a living, contextual layer rather than a static input.
Why Technology Alone Fails
The primary failure of the tech-first approach is behavioral. Despite the sophistication of machine learning, many consumers are fundamentally unwilling to engage in the intimate, sometimes invasive, process of body scanning. Beyond privacy concerns, there is a psychological barrier: being presented with an objective, uncompromising 3D representation of one’s body is rarely a positive consumer experience. When a technology barrier is placed between the act of browsing and the checkout, shoppers frequently abandon their carts, choosing instead to rely on the "living room fitting room."
Furthermore, the data foundations upon which these technologies are built are often flawed. Many brands operate using "blocks"—the fundamental patterns from which all sizes are graded—that have not been updated for decades. As noted by industry experts like Michaela Wessels of Style Arcade, distorted retail data often leads companies to miscalculate inventory replenishment and underestimate the true bottom-line impact of poor fit. When brands rely on third-party suppliers to maintain these blocks, they lose the ability to refine fit based on real-world consumer feedback.
The Subjectivity of "Fit"
The most significant hurdle is that "fit" is a subjective preference, not a mathematical absolute. A shopper’s definition of comfort is influenced by social, cultural, and personal factors that a digital avatar cannot easily interpret.
Consider the impact of health and lifestyle trends. The widespread adoption of GLP-1 medications, for example, has caused rapid, significant changes in body composition for a large demographic. Similarly, the rise of strength training in women’s fitness has challenged the traditional hourglass grading rules used in pattern making. These trends mean that bodies are changing faster than the industry’s linear, outdated grading guidelines can track. When a brand designs for a "fit model" rather than a diverse, fluctuating population, the resulting garments will inevitably fail to satisfy the majority of the market.
Integrating Intelligence: The Path Forward
The solution for 2026 and beyond is not the search for a "silver bullet" technology, but the adoption of holistic, data-driven platforms. Companies like SAIZ are leading this shift by integrating what they term "Fit Intelligence." This approach does not merely suggest a size; it creates a connected data loop.
By linking manufacturing data, merchandising spreadsheets, and real-time consumer return patterns, these platforms allow brands to make informed decisions about their core blocks. This is not just about telling a customer which size to buy; it is about ensuring that the size being offered is actually relevant to the brand’s current customer base.
Strategic Implications for Retailers
For retailers looking to mitigate the impact of returns, the investment strategy must change. Relying solely on a "monolithic" technology solution is no longer a viable path to profitability. Instead, ROI should be measured by the following metrics:
- Cultural Auditing: Brands must audit their internal sizing standards against current, diverse population data rather than relying on historical "ideal" models.
- Widget Integration: Recommendation engines must be user-friendly, prioritizing ease of use over deep biometric data collection.
- Feedback Loops: Retailers must create a direct, seamless channel for consumers to express their fit preferences, which should then inform future design and inventory production.
- Narrative-Driven Commerce: Because consumers often purchase for a "look" rather than a measurement, the digital experience must effectively communicate the intended fit (e.g., "relaxed," "oversized," "tailored") alongside technical sizing.
The return on investment in fit technology is moving away from purely technical gains and toward a more profound goal: building trust. When a brand can accurately predict and communicate how a garment will feel on a specific individual, they are no longer just selling a product; they are offering a service. In this new era, the brands that succeed will be those that view fit not as a technical problem to be solved, but as a long-term conversation with the consumer. By blending scientific body data with the subjective realities of personal preference, the industry can finally move away from the unsustainable "wardrobing" culture that has plagued it for far too long.