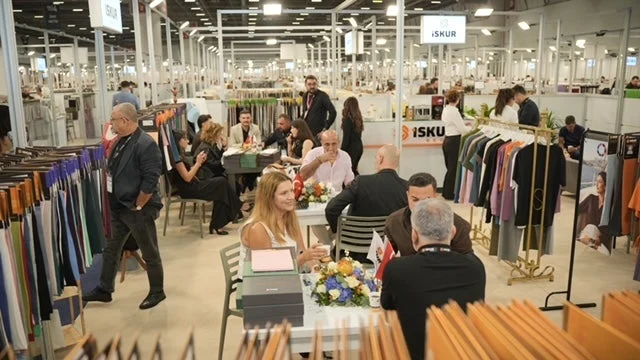
The Turkish textile and apparel sector, a cornerstone of the nation’s manufacturing economy and a vital link in the global fashion supply chain, is currently navigating a severe financial crunch as companies attempt to align with stringent international environmental regulations. While manufacturers recognize the imperative to pivot toward sustainable production models, circular economies, and lower-carbon footprints, access to the capital required for this transformation has become a critical bottleneck. Industry stakeholders, trade associations, and factory owners report that high interest rates, tight credit conditions, and escalating compliance costs are leaving many Turkish suppliers unable to finance the necessary technological and infrastructural overhauls.
Background Context of the Crisis
Turkey has long maintained its position as one of the world’s leading textile and garment exporters, prized by global brands and retailers for its geographical proximity to European markets, rapid turnaround times, and high-quality craftsmanship. The sector accounts for a significant share of Turkey’s total export revenue and employs hundreds of thousands of workers across regions such as Istanbul, Bursa, Denizli, and Izmir.
However, the operating environment for these suppliers has shifted dramatically in recent years. Regulatory pressures from major export destinations—most notably the European Union—have intensified. Initiatives such as the European Green Deal, the EU Strategy for Sustainable and Circular Textiles, and incoming due diligence directives are demanding unprecedented transparency, traceability, and environmental accountability from supply chain partners. Global fashion brands are increasingly pushing these compliance obligations down to their tier-one and tier-two suppliers, often requiring them to secure certifications, reduce water and energy consumption, transition to renewable energy sources, and adopt recycled or organic materials.
For Turkish manufacturers, meeting these demands requires substantial capital expenditure. Upgrading machinery to energy-efficient models, installing wastewater treatment facilities, adopting digital tracking systems, and auditing supply chains demand investments that many smaller and medium-sized enterprises (SMEs) simply cannot afford under current financial constraints.
The Financial Landscape and Credit Squeeze
The primary impediment to Turkey’s green transition in textiles is macroeconomic instability coupled with tight monetary policy. In an effort to curb high domestic inflation, the Central Bank of Turkey implemented a series of aggressive interest rate hikes, driving borrowing costs to levels not seen in decades. For capital-intensive industries like textiles, which operate on notoriously tight profit margins, securing commercial bank loans to fund long-term sustainability projects has become cost-prohibitive.
Commercial lenders are increasingly risk-averse, offering short-term loans with high interest rates that are misaligned with the multi-year return-on-investment timelines associated with sustainability upgrades. Green financing instruments and sustainability-linked loans, which are more readily available in Western markets, remain underdeveloped or difficult for Turkish SMEs to access due to strict collateral requirements and complex administrative procedures.
Consequently, many suppliers find themselves trapped in a paradox: failing to invest in sustainability risks losing international buyers who are bound by their own corporate ESG (Environmental, Social, and Governance) targets, yet investing in sustainability risks immediate insolvency due to unsustainable debt servicing.
Chronology of Regulatory Pressures and Market Shifts
The escalation of the funding crisis can be traced through several key phases over the past five years:
2019–2020: The European Union unveils the European Green Deal, setting the overarching framework for climate neutrality by 2050. Major European fashion brands begin formulating internal sustainability roadmaps, signaling to overseas suppliers that environmental metrics will soon carry equal weight with price and delivery speed.
2021–2022: Post-pandemic supply chain disruptions prompt a re-evaluation of nearshoring, initially boosting Turkish exports as brands sought alternatives to Asian manufacturing hubs. Concurrently, energy prices surge following geopolitical conflicts in Europe, exposing the high energy dependency and inefficiency of many Turkish textile mills and dyeing houses.
2023: The Turkish domestic economy experiences significant monetary tightening. Inflationary pressures drive up labor, material, and operational costs. Meanwhile, the EU introduces specific legislative proposals targeting green claims, corporate sustainability reporting, and waste management, setting strict compliance deadlines for the mid-2020s.
2024–Present: The financial squeeze peaks. While international buyers increasingly mandate verifiable reductions in carbon emissions and chemical usage, Turkish suppliers report widespread difficulties in obtaining bank financing. Trade bodies issue warnings that without targeted financial intervention, international credit lines, or public subsidies, a wave of consolidation or closures could sweep through the manufacturing base.
Supporting Data and Economic Metrics
Industry reports and economic analyses underscore the depth of the challenge facing Turkish textile exporters:
- Margin Compression: Operating margins for Turkish apparel manufacturers have shrunk by an estimated 3 to 5 percentage points over the past two years, driven by rising local production costs and currency fluctuations.
- Compliance Costs: Upgrading a mid-sized textile dyeing and finishing facility to meet modern European environmental standards can require capital investments ranging from several hundred thousand to millions of dollars, depending on the scale of water recycling and energy recovery systems needed.
- Export Vulnerability: Over 70% of Turkey’s textile and apparel exports are directed toward the European Union, making the sector uniquely vulnerable to European regulatory shifts such as the Carbon Border Adjustment Mechanism (CBAM) and extended producer responsibility rules.
- SME Dominance: Small and medium-sized enterprises make up the vast majority of the Turkish textile ecosystem. Unlike multinational conglomerates, these entities lack internal treasury reserves to self-finance major capital expenditures.
Industry Reactions and Stakeholder Perspectives
Representatives from leading Turkish trade organizations, including the Turkish Exporters Assembly (TIM) and various regional textile and apparel associations, have increasingly voiced alarm over the situation. In recent statements, industry leaders have emphasized that Turkish manufacturers are fully committed to sustainable production and understand that ecological compliance is no longer optional. However, they argue that the burden of the transition cannot rest solely on the shoulders of manufacturers who are simultaneously grappling with high domestic inflation and depressed global consumer demand.
According to sector advocates, public-private partnerships and targeted green financing mechanisms are urgently required. Manufacturers are calling for government-backed guarantee funds, low-interest green loans, and grants specifically earmarked for environmental technology adoption. Without such interventions, industry stakeholders warn that Turkey risks losing its competitive edge to rival sourcing destinations in Asia and North Africa where compliance pressures may be less immediate or where state-backed green subsidies are more robust.
Conversely, representatives from international fashion brands and buying offices maintain that their sustainability targets are non-negotiable, driven by consumer expectations and mandatory reporting laws in their home markets. While some large retailers have initiated supplier-development programs—offering technical assistance and, in rare cases, co-investments to help critical suppliers decarbonize—these initiatives often cover only a fraction of the broader supply chain, leaving the majority of independent suppliers to fend for themselves.
Broader Impact and Strategic Implications
The inability of Turkish textile suppliers to adequately fund their sustainability transition carries significant implications for the global fashion landscape.
For European and international brands, a supply chain crisis in Turkey could disrupt sourcing strategies at a time when nearshoring and supply chain resilience are paramount. If Turkish suppliers are forced to scale back operations or exit the market due to compliance failures, brands may face reduced sourcing capacity, increased prices, or the complex task of qualifying new suppliers in alternative regions.
For the Turkish economy, the stakes are equally high. The textile and apparel sector is a major net exporter and a crucial generator of employment, particularly for women in regional manufacturing hubs. A prolonged credit crunch that undermines the sector’s viability could lead to job losses, reduced export revenues, and a broader dampening effect on regional economic stability.
Ultimately, navigating this financial impasse will require coordinated action among Turkish policymakers, commercial financial institutions, and global brand partners. Developing accessible green finance frameworks, restructuring high-interest debt, and sharing the financial responsibility of the ecological transition across the entire supply chain will be essential to ensure that Turkey’s textile industry can maintain its historical prominence in a more sustainable global economy.