When Transparency Becomes Costly: Navigating the Financial and Operational Realities of Modern Apparel Supply Chains

The global apparel industry stands at a critical juncture where the rising demand for supply chain transparency increasingly collides with economic realities. For decades, consumers, regulatory bodies, and advocacy groups have pushed brands and manufacturers to disclose the origins of their garments, the working conditions in partner factories, and the environmental impact of their production cycles. However, as new regulations take effect across major markets like the European Union and North America, stakeholders are discovering that absolute visibility carries a heavy price tag. Far from being a simple marketing tool or a box-checking exercise, deep supply chain traceability requires substantial capital investment, technological overhauls, and complex data management systems. As margins tighten and inflationary pressures persist, companies are grappling with a fundamental question: Can the industry sustain the escalating costs of being transparent?
Background Context and Regulatory Pressures
The push for supply chain transparency is not a passing trend; it is a structural transformation driven by legislative mandates and shifting consumer expectations. Historically, apparel supply chains have been notoriously opaque. Brands frequently outsourced production to multi-tiered networks of subcontractors, making it difficult to track where raw materials were sourced, who dyed the fabrics, and who stitched the final garments. This lack of visibility historically shielded companies from accountability regarding labor rights violations, environmental degradation, and resource depletion.
In recent years, however, governments have stepped in to dismantle this opacity. The European Union has spearheaded some of the most aggressive legislative measures, including the Corporate Sustainability Due Diligence Directive (CSDDD) and proposed bans on products made with forced labor. Simultaneously, the United States has enforced stricter enforcement of the Uyghur Forced Labor Prevention Act (UFLPA), requiring importers to provide clear, verifiable proof that goods entering the country are free from forced labor at every tier of the production process.
These regulatory frameworks have fundamentally altered the risk landscape. Non-compliance no longer results merely in reputational damage; it leads to seized shipments, substantial financial penalties, and potential legal liability for corporate executives. Consequently, apparel firms have been forced to transition from voluntary sustainability reporting to mandatory, rigorous traceability systems.
The Financial Burden of Traceability
Implementing comprehensive supply chain visibility requires deploying advanced technologies such as blockchain, radio-frequency identification (RFID), digital product passports (DPPs), and enterprise resource planning (ERP) software. While these tools offer unprecedented tracking capabilities, their implementation is capital-intensive.
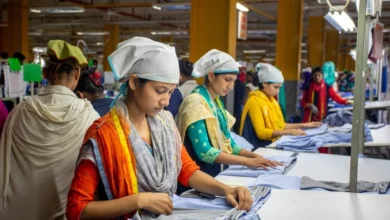
Small and medium-sized enterprises (SMEs) within the apparel sector face a disproportionate disadvantage. Unlike multinational conglomerates with dedicated compliance divisions and robust IT budgets, smaller brands often struggle to absorb the upfront costs of software integration and third-party auditing. Furthermore, suppliers—often operating on razor-thin margins in developing economies—are frequently expected to shoulder the burden of collecting and transmitting granular data up the supply chain without receiving financial compensation from buying brands.
Data from recent industry surveys indicate that companies investing in comprehensive supply chain mapping report an initial operational cost increase of 3% to 7%. These expenses stem from multiple sources:
- Software licensing and infrastructure upgrades to manage real-time data flows.
- Increased frequency of independent audits and on-site factory inspections.
- Personnel training and hiring specialized compliance officers.
- Managing data verification challenges, as manual record-keeping by lower-tier suppliers often leads to discrepancies.
A Chronology of the Transparency Movement
To understand how the industry arrived at this financial crossroads, it is necessary to examine the evolution of supply chain transparency over the past two decades.
The Rana Plaza disaster in Bangladesh served as a watershed moment for the global garment industry. The collapse of the eight-story commercial building, which housed several garment factories, resulted in the deaths of more than 1,100 workers and injured thousands more. In the immediate aftermath, public outrage forced brands to acknowledge their lack of oversight regarding subcontractor safety. This tragedy catalyzed the creation of legally binding factory safety accords and marked the beginning of public supplier list disclosures by major fast-fashion and luxury brands.
Throughout the late 2010s, transparency evolved from factory-level disclosures to material-level tracking. Consumers and investors began demanding to know not just where a garment was sewn, but where the cotton was grown, how the polyester was manufactured, and what chemicals were used in the finishing processes. Organizations like Fashion Revolution published annual transparency indices, publicly ranking brands based on how much information they shared about their operations.
By the early 2020s, transparency transformed from a voluntary corporate social responsibility (CSR) initiative into a legal requirement. The introduction of the EU Strategy for Sustainable and Circular Textiles set a clear timeline for the mandatory implementation of Digital Product Passports by the middle of the decade. This transition shifted the conversation from whether brands should disclose their supply chains to how they could afford to do so accurately and efficiently.
Industry Reactions and Stakeholder Perspectives
As the financial and operational realities of these mandates set in, reactions from across the apparel ecosystem have been mixed. Industry leaders recognize the long-term benefits of resilient, transparent supply chains, yet they voice legitimate concerns regarding implementation speed and cost distribution.
Representatives from major manufacturing associations have pointed out that transparency initiatives often exacerbate power imbalances within the supply chain. Large brands hold the leverage to demand extensive data reporting, yet they rarely share the financial burden with Tier 2, Tier 3, and raw material suppliers. Industry advocates argue that unless brands adopt collaborative funding models—such as paying higher unit prices to offset compliance costs—smaller suppliers may be forced out of business, leading to increased market consolidation.
Conversely, consumer advocacy groups and labor rights organizations maintain that the cost of transparency is a necessary price for ethical production. Activists argue that the true cost of apparel has long been subsidized by exploited labor and environmental degradation in the Global South. From this perspective, the financial investments required for traceability simply internalize costs that were previously ignored.
Financial analysts studying the retail sector note a growing divergence between companies that view transparency as a strategic investment and those that treat it as a regulatory compliance burden. Firms that successfully integrate traceability into their core operations often find ancillary benefits, such as optimized inventory management, reduced waste, and enhanced brand loyalty among conscious consumers. However, poorly executed transparency initiatives can drain corporate liquidity without yielding meaningful improvements in sustainability or consumer trust.
Implications for the Future of Global Apparel
The intersection of cost and transparency will likely define the trajectory of the global apparel industry for the foreseeable future. As regulatory enforcement tightens and digital infrastructure matures, several key implications are emerging for brands, manufacturers, and consumers.
First, market consolidation is expected to accelerate. Well-capitalized brands and large conglomerates are better positioned to absorb the technology and auditing expenses associated with deep traceability. Smaller independent brands may find themselves priced out of compliance, necessitating cooperative models or shared service platforms to pool resources.
Second, technology adoption will shift from experimental pilots to mandatory operational baselines. Technologies that can automate data collection and verify the provenance of raw materials—such as molecular tagging for cotton and synthetic fibers—will move from niche solutions to industry standards. However, the success of these technologies depends heavily on standardization and interoperability across different platforms.
Third, pricing structures for end consumers are bound to shift. As brands internalize the costs of comprehensive supply chain auditing, fair-wage verification, and sustainable material sourcing, the era of ultra-cheap fast fashion may face insurmountable economic headwinds. Consumers will likely encounter higher price points for garments that carry verified claims of ethical and sustainable production.
Ultimately, when transparency becomes costly, it forces the apparel industry to confront its structural inefficiencies. While the financial burden in the short term is undeniable, the long-term viability of the global garment trade depends on building supply chains that are not only visible, but resilient, equitable, and economically sustainable for all participants involved.