Bath And Body Works Reports Q2 2026 Earnings As Consumer First Formula Turnaround Strategy Gains Traction Amid Retail Expansion

Bath & Body Works released its financial results for the second quarter of fiscal 2026 on Wednesday, detailing a modest dip in net sales that leadership nevertheless framed as validation of an ongoing multi-year corporate pivot. The Ohio-based fragrance and body-care giant reported net sales of $1.5 billion, representing a 2.3% decrease compared to the same period in the previous year. Despite the top-line contraction, executive leadership characterized the performance as entirely in line with internal projections, signaling that the organization’s overarching transformation framework—dubbed the "Consumer First Formula"—is operating according to schedule.
The financial disclosure arrives nine months into a comprehensive strategic overhaul initiated by CEO Daniel Heaf. Designed to stabilize the brand, modernize its product portfolio, and broaden its market reach, the turnaround plan has forced significant operational shifts. While Wall Street continues to scrutinize legacy brick-and-mortar metrics against digital acceleration, executive leadership maintains that patience is required for a retail restructuring of this magnitude.
Navigating the Turnaround: Q2 2026 Financial Overview and Executive Perspective
During the earnings call, CEO Daniel Heaf addressed both the underlying pressures facing the business and the deliberate pacing of the corporate strategy. While acknowledging that short-term performance has not yet reached the ultimate ambitions of the board, he emphasized that meeting expectations during a foundational transition period is a critical milestone.
"While the underlying business remains pressured and our performance is not yet where we want it to be, we are where we expect it to be," said Heaf. "We have been clear since introducing the Consumer First Formula nine months ago that returning Bath & Body Works to sustainable growth is a multi-year transformation."
The 2.3% decline to $1.5 billion in net sales reflects an operating environment where consumer discretionary spending remains volatile. Inflationary pressures, shifting consumer preferences toward experiential retail, and the complexities of migrating legacy supply chains have all tested mid-tier specialty retailers. However, Bath & Body Works’ leadership is betting that targeted investments in new distribution channels, celebrity-backed product franchises, and rigorous portfolio pruning will insulate the brand against broader retail headwinds and set the stage for durable, long-term profitability.
Expanding the Footprint: Strategic Growth Across Amazon and Ulta Beauty
A central pillar of Heaf’s growth strategy involves meeting modern consumers where they shop by expanding distribution beyond the company’s traditional proprietary channels. This philosophy manifested in two major retail partnerships: a curated digital storefront launched on Amazon in February, and a physical retail rollout across select Ulta Beauty stores beginning in July.
The channel diversification is already yielding measurable results. According to executive commentary, sales on Amazon tripled during the second quarter compared to the first quarter of the fiscal year. More importantly, the demographic profile of the Amazon consumer is skewing advantageously for the brand.
"The channel is attracting a higher mix of new-to-brand consumers who skew younger and more affluent while delivering a higher average unit retail than our own channels, reinforcing our confidence that Amazon can expand our reach and drive incremental growth," Heaf explained.
Meanwhile, the partnership with Ulta Beauty, though in its nascent stages, has capitalized on consumer demand for accessible trial-sized products within a dedicated prestige beauty environment. Crucially, leadership addressed persistent investor concerns regarding channel cannibalization—the fear that third-party partnerships might siphon foot traffic and digital orders away from official Bath & Body Works properties. Heaf asserted that the Amazon and Ulta channels are additive rather than cannibalistic, serving distinct psychological and logistical needs for the consumer base.
To complement these external partnerships, the company simultaneously adjusted its physical store portfolio during the quarter. Bath & Body Works opened 24 new brick-and-mortar locations—focusing primarily on off-mall strip centers that offer lower overhead and higher convenience—while closing 10 traditional mall-based stores. Additionally, international franchise partners opened 17 new storefronts globally, underscoring a disciplined approach to physical real estate optimization.
"At the end of the day, we’re not expanding our distribution to just add more doors," Heaf noted. "We’re really going after new consumers, and each partnership has a distinctive strategic need. Amazon is about convenience, and Ulta is about trial and discovery within a specialty beauty environment. If you want the full Bath & Body Works experience, you want all of our seasonal products, you want our collabs, our own channels are still the places to go and get that."
Product Innovation, Celebrity Partnerships, and Franchise Discipline
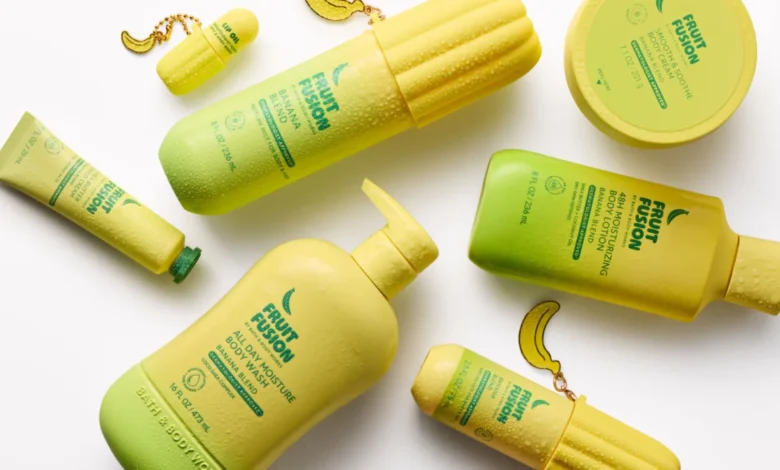
Beyond distribution adjustments, the corporate turnaround relies heavily on product innovation and sophisticated marketing. In July, the company launched its Fruit Fusion body-care franchise, supported by a high-profile marketing campaign fronted by actress and entrepreneur Hilary Duff. The initiative marks the first time Bath & Body Works has deployed a major celebrity ambassador for a core product line.
Leveraging digital-first strategies, the Fruit Fusion rollout was amplified by social media content creators and integrated directly into the brand’s new Amazon storefront. Management intends to use this launch as a repeatable playbook for upcoming campaigns, with plans to introduce two additional scents to the Fruit Fusion line during the third quarter.
This emphasis on franchise management represents a deliberate return to the core competencies that historically fueled the brand’s market dominance. Rather than scattering promotional energy across fleeting, short-lived items, the company is prioritizing cohesive, long-standing product families.
"The other important point about Fruit Fusion, which is a big learning and I think a return to what Bath & Body Works does so well, is franchise management," Heaf stated. "Fruit Fusion isn’t in this door and out the next. We are really getting back to that disciplined franchise management that the business was known for."
The company is also doubling down on its successful Everyday Luxuries franchise. Originally launched to offer accessible interpretations—or "dupes"—of popular designer and luxury fragrances, the line will be expanded in the second half of the year. Responding directly to consumer demand for high-longevity scents, the reformulated products will feature "higher fragrance loads" to increase olfactory intensity and persistence.
Concurrently, Bath & Body Works continues to refine its home-fragrance offerings. While candles remain a foundational pillar of the business—highlighted by the scheduled Monday launch of the elevated, luxury-tier Reserve Collection—the company is making difficult cuts in peripheral categories to streamline operations.
Streamlining Operations: Exiting the Home Care Category
As part of the ongoing portfolio rationalization under the Consumer First Formula, Bath & Body Works announced it will completely shutter its home category, which includes specialized laundry detergents and kitchen cleaning products.
The decision was driven by rigorous cost-benefit analyses that revealed diminishing returns on operational complexity. According to company figures, the home category accounted for less than 1% of the brand’s annual net sales. Despite this minimal revenue contribution, maintaining the category demanded disproportionate supply chain resources, packaging adjustments, and regulatory compliance oversight. By eliminating these non-core products, the company aims to reduce operational friction and redirect capital toward high-margin, high-growth body care and core home-fragrance lines.
"The category represents less than 1% of our annual sales and creates disproportionate product and operating complexity, without generating the productivity or incremental demand required to justify the cost," Heaf said.
Industry Context and Analytical Outlook
The strategic moves executed by Bath & Body Works during the second quarter of fiscal 2026 underscore a broader structural evolution within the specialty beauty and personal care sector. As digital marketplaces mature and consumer loyalty fragments across a proliferating array of independent and legacy brands, legacy specialty retailers are increasingly forced to reevaluate distribution exclusivity.
For decades, Bath & Body Works relied on a strictly vertical retail model, wherein products were available exclusively through company-owned brick-and-mortar stores and its proprietary e-commerce portal. While this model protected brand equity and gross margins during periods of steady economic expansion, it ultimately limited customer acquisition channels as younger consumers shifted their discovery habits toward multi-brand digital marketplaces like Amazon and specialty beauty chains like Ulta Beauty.
The early success of the Amazon channel—evidenced by a threefold sales increase and the capture of younger, more affluent shoppers—suggests that opening secondary distribution channels can serve as an effective top-of-funnel customer acquisition engine. However, maintaining brand prestige while scaling through third-party platforms remains a delicate balancing act for executive leadership. The ability to preserve higher average unit retail (AUR) values on Amazon indicates that brand equity has remained resilient thus far, mitigating fears of brand dilution.
Simultaneously, the pruning of underperforming inventory, such as the discontinuation of the home care category, reflects a broader corporate austerity trend observed across the retail sector. In an economic climate characterized by persistent cost pressures and cautious consumer spending, companies are increasingly prioritizing margin protection and operational simplicity over top-line revenue expansion derived from low-productivity SKUs.
Future Outlook for the Multi-Year Transformation
As Bath & Body Works navigates the remainder of fiscal 2026, the focus will remain squarely on executing the remaining phases of the Consumer First Formula. Investors and analysts will closely monitor the performance of upcoming product launches, such as the expanded Everyday Luxuries line and the luxury-tier Reserve Collection candles, to determine whether elevated product formats can successfully drive same-store sales growth.
Furthermore, the ongoing integration into Ulta Beauty stores will be evaluated for its long-term capacity to drive trial and discovery without cannibalizing core retail traffic. With international partners continuing to open brick-and-mortar doors and digital channels scaling efficiently, Bath & Body Works is attempting a complex high-wire act: modernizing its operational infrastructure while honoring the heritage of accessible fragrance and body care that defined its decades-long market leadership.
While top-line pressures persist in the near term, leadership remains confident that disciplined franchise management, targeted retail expansion, and a relentless focus on consumer preferences will eventually steer the company back toward sustained, profitable growth.